
Finance
GameStop stock: Making sense of the madness
What’s happening and why


Late last week, Reddit woke up to a strange but oddly foreboding revolution: a call to buy stock from ailing video game store GameStop. The trend’s seeds, an explosive thread from the oft underrepresented but equally as chaotic subreddit r/WallStreetBets, spoke of the stock’s inherent strength after a period of stagnation borne from the pandemic. Naturally, no one believed the seemingly meme-worthy claim.
Now, a week later, GameStop is one of the most profitable stocks on Wall Street, to everyone’s surprise. If you weren’t on Reddit when everything went haywire, you’re likely wondering what happened. Why is GameStop trending? Should you buy GameStop stock now? It’s not as simple as 1-2-3.
The tech players
On the tech side of things, the biggest two factors are, obviously, Reddit and, less obviously, micro-investing apps.
Last year, a heavy r/WallStreetBets user, u/DeepFuckingValue, heavily speculated on GameStop’s eventual success. The Redditor poured in US$ 50,000 for shares in GME. In investing as much into the seemingly dying stock, they, along with others who followed in their path, hoped to cause a short squeeze on all those who bet options on its failure.
This is where micro-investing apps come in. r/WallStreetBets is not a community for investment firms or professionals. Most of the community are middle-class Americans, trying to find the next big pick for a quick buck. That said, the requirements of more robust investing firms are often too steep for the average American. Like Robinhood and Webull, micro-investing apps allow users to purchase stocks without a minimum required and easily from their phone.
With an easy-to-use app, r/WallStreetBets raised an army of GME buyers, which rapidly skyrocketed the stock’s price. The stock was up 6000 percent since its low point last summer. While Reddit gained traction as the trend went along, other investors saw the trend and bought into it without even knowing about Reddit’s involvement until it was too late.
So how did a Reddit community take down a hedge fund?
To understand how the Redditors managed to take on hedge funds with billions of assets under management, we need to understand the meaning of a “short.” A short is when a trader borrows stock from a broker and immediately sells it at the current price. The brokers, in this case, are micro-investing apps like Robinhood.
On an ordinary day, if you buy Stock A for US$ 10 and sell it for US$ 12, your realized profit is said to be US$ 2. This is the fundamental concept on which every business runs. On the other hand, a short-seller places a bet that the stock price will fall so that they can purchase the stock back at a lower price and return it to the broker. In this case, they profit from the difference between the original price at which the stock was sold and the price at which it was repurchased.
In simpler terms, if the trader borrowed the stock for US$ 12 and repurchased it at US$ 10, the realized profit is said to be US$ 2. But the risk involved is equally the same. If the stock price does not decrease like the trader had expected and rises to US$ 14, the trader ends up taking a loss of US$ 2 because they have borrowed the stock from the broker and need to pay for it.
In GME, Melvin Capital, a hedge fund based out of New York, had bets against the stock by short-selling its shares. Members of r/WallStreetBets decided to start accumulating GME so that the price climbs and inflicts a loss on Melvin’s short. The move is called a “short squeeze” and took the stock’s value from US$ 17 (at the beginning of 2021) to US$ 150 when trading closed on January 26.
Seeing GME climb unrealistic valuations, it soon caught the attention of pretty much every trader or investor in the US. What started as a micro-managed movement against a hedge fund became a widespread revolt against the bears. In the end, Melvin was forced to close its position on GME and had to take external support from its backers Citadel and Point72, who pumped US$ 3 billion in the fund to keep it alive.
A micro class war
Unsurprisingly, bigger investors hated GME’s sudden uptrend. The success went against everything their system stood for. In fact, a lot of them called for an official investigation against Reddit for market manipulation. The calls, however, haven’t materialized into any solid repercussions at the time of this writing.
And why would they? As liberal politician Alexandra Ocasio-Cortez (AOC) put it, “it’s really something to see Wall Streeters with a long history of treating our economy as a casino complain about a message board of posters also treating the market as a casino.” Reddit was merely playing the same game as Wall Street.
Out of political options, Wall Street then went after Reddit’s trade tools, the same micro-investing apps that touted a democratized stock market for the middle class. As of Thursday, Robinhood and its contemporaries have stopped or limited buying any more Reddit-implicated stocks. Investors can only sell, but no one is budging. Soon after the announcement, AOC (and surprisingly, Republican Ted Cruz) is pushing for a formal investigation against Robinhood for market manipulation, the same accusation levied against Reddit.
And so, the meme-worthy investing boom turned into a micro class war between the tough-as-nails, nothing-to-lose Redditors versus long-standing, ultra-rich investors. Echoing the remnants of the Occupy Wall Street movement from years past, both parties are now locked in a tense game of chicken to see who blinks first.
To Wall Street’s dismay, the investors of Reddit have almost nothing to lose and absolutely everything to gain. Most have already inured themselves to heavy losses on the stock market. If Wall Street wants to complete, they will be forced to expose their system’s double standards against the average investor.
The repercussions of the war
For most, it’s revenge. The whole point of the short squeeze was to make brokers and funds lose money. We are a crucial junction in time where we’re seeing the norms of capitalism getting challenged. The rich have always jokingly said that the stock market is open for all and that anyone can be rich by leveraging it.
Well, a few folks took it quite seriously and decided to unleash the market’s true potential. Turning the tables in one’s favor. It isn’t just GameStop. Reddit users have started encouraging people to buy shares in Blackberry and AMC theaters.
This is a truly modern, digital, and anonymous vigilantism. People are fed up with the 1 percent and are hitting back in whichever way possible. However, the GME saga has clearly shown us the prime drawbacks of the system. In response to the stock’s unrealistic climb, Robinhood would restrict trading for GameStop and others, effectively preventing investors from purchasing more shares of the stocks. For an app that’s focused on democratizing finance for all, this isn’t a confidence-building measure.
According to Financial Times, US$ 39 million of Robinhood’s revenues come from equities, and options order flow comes from Citadel Securities, a part of Citadel. And it repressed a whopping 35 percent of Robinhood’s revenues. Can two financial institutions rub each other’s backs while smaller clients (retail investors) are left to fend for their own?
Many experts have pointed out that the future of the stock markets will be in everyone’s hands and not just institutions. Even though individuals were always allowed to use the exchanges, they never had any considerable central power against larger funds.
In a nutshell, Reddit has forced the world to reconsider our fundamental financial systems and how they’re played by a few too powerful players. The White House and the SEC are both monitoring the situation with GameStop and the larger stock market.




Visa’s latest report shows growing interest in digital remittances and stablecoins in the Philippines. However, many Filipinos still lack confidence in using stablecoins to send or receive money.
The Money Travels: 2026 Digital Remittances Adoption report surveyed more than 45,000 remittance senders and receivers across 20 markets. It found that 45% of Filipino respondents received money from overseas in the past 12 months, making the Philippines the most receiver-led market among the six Asia-Pacific markets surveyed.
The report also found that 72% of Filipino respondents send or receive money multiple times a year, while around 35% do so monthly. Many rely on remittances to cover essential expenses and support family members.
Filipinos turn to digital remittances
Digital channels are becoming an important way for Filipinos to receive money from overseas.
According to Visa, 44% of Filipino respondents said mobile wallets provide the fastest access to transferred funds, with money arriving instantly. Direct bank transfers followed at 31%, while debit or credit card transfers through apps or websites came in at 20%.
By comparison, only 18% said in-person transfers through banks, money transfer agents, or stores provide instant access to funds.
The report also found that 27% of respondents struggle to make transactions outside normal banking hours. Only 19% reported using physical money transfer agents or stores.
These findings highlight the appeal of digital remittances for Filipinos who want convenient access to money sent from overseas.
Stablecoin awareness grows, but trust remains low
Visa’s report examined consumer awareness and perceptions of stablecoins for the first time.
Stablecoins are digital assets designed to maintain a relatively stable value, often by being tied to a currency such as the US dollar. Unlike cryptocurrencies with highly volatile prices, stablecoins aim to minimize price fluctuations.
The report found that 42% of Filipino respondents have some awareness of stablecoins. However, only 38% trust stablecoin transfers. That figure falls well below trust in digital remittances at 79% and cash remittances at 81%.
Despite this gap, 79% of respondents want to learn more about stablecoins and how they work.
The government emerged as the most trusted entity for handling digital currencies, with 70% of respondents expressing trust. Global payment networks such as Visa followed at 68%.
These findings suggest that consumer education alone may not be enough to encourage adoption. Payment providers must also build confidence in the security and reliability of stablecoin transfers.
Visa explores stablecoins for cross-border payments
Visa is exploring stablecoins as part of its efforts to improve cross-border money transfers.
The company launched Visa Direct more than a decade ago to facilitate money transfers and payouts. In the Philippines, it partnered with USSC in April 2025 and RCBC in August 2025 to expand its money movement services.
Visa Direct enables participating financial institutions, remittance providers, and businesses to send funds to bank accounts, cards, and digital wallets.
Stablecoins could help financial institutions fund and settle international payouts. This approach could make it more efficient to move money between markets while allowing recipients to receive funds in their local currency, depending on how the service operates.
However, faster settlement between financial institutions does not automatically mean lower fees or faster access to money for consumers. The actual benefits will depend on how providers implement these services and whether they pass any savings on to customers.
“Visa continues to be at the forefront of shaping global money movement and enabling faster as well as more secure and seamless money transfers will help build trust in emerging digital remittance methods and technologies such as stablecoins,” said Jeffrey Navarro, Country Manager for Visa Philippines.
Navarro added that Visa would continue working with regulators, banks, and fintech partners to make money transfers more responsive to the needs of Filipino consumers.
Can stablecoins improve remittances for Filipinos?
Remittances remain an important source of financial support for Filipino households. Visa found that respondents primarily send or receive money to cover essential expenses (34%) and fulfill family or cultural obligations (33%). Another 30% cited gifts for holidays or special occasions.
Stablecoins could offer another way to move money across borders, particularly if they help payment providers settle transactions more efficiently. However, Visa’s findings reveal a gap between consumer awareness and confidence in the technology.
For now, the results point to an opportunity for payment providers to explain how stablecoins work and how they compare with existing remittance options.
Whether stablecoin-based transfers can meaningfully reduce costs, speed up payments, or improve access to funds for Filipino families remains to be seen.
The Money Travels 2026 study was conducted by Morning Consult on behalf of Visa from February 24 to March 2, 2026. It surveyed more than 45,000 remittance senders and receivers across 20 markets. The findings are based on self-reported responses and reflect consumer awareness, attitudes, and stated intentions rather than actual adoption or operational availability.
Finance
HONOR, Fidesmo partner for contactless payments across Europe, Middle East
Enabling contactless payments on the HONOR Watch 6

HONOR and Fidesmo have partnered to launch contactless payments across Europe and the Middle East on the HONOR Watch 6.
Powered by Fidesmo Pay, the integration enables users to connect an existing Mastercard or Visa card to their watch and complete contactless transactions directly from the wearable device.
This brings Fidesmo’s network of over 900 banks and financial institutions to HONOR’s customers. Users can connect an existing card to the HONOR Watch 6 instantly through the HONOR Health App, which installs a unique token directly onto the watch.
Acting as a secure reference to the payment method, this token allows customers to pay without storing their actual payment details on the device. Once installed, users can tap the watch at any
contactless terminal to pay, just as they would with a card or phone.
HONOR joins a group of device partners that already includes Swatch, Polar, and Mondaine as Fidesmo continues to build momentum across categories.
Features
Getting the latest Samsung Galaxy Z Flip8 at 0% Interest with Maya Mini Payments
What convinced me to upgrade and how Maya Mini Payments made paying for it easier~

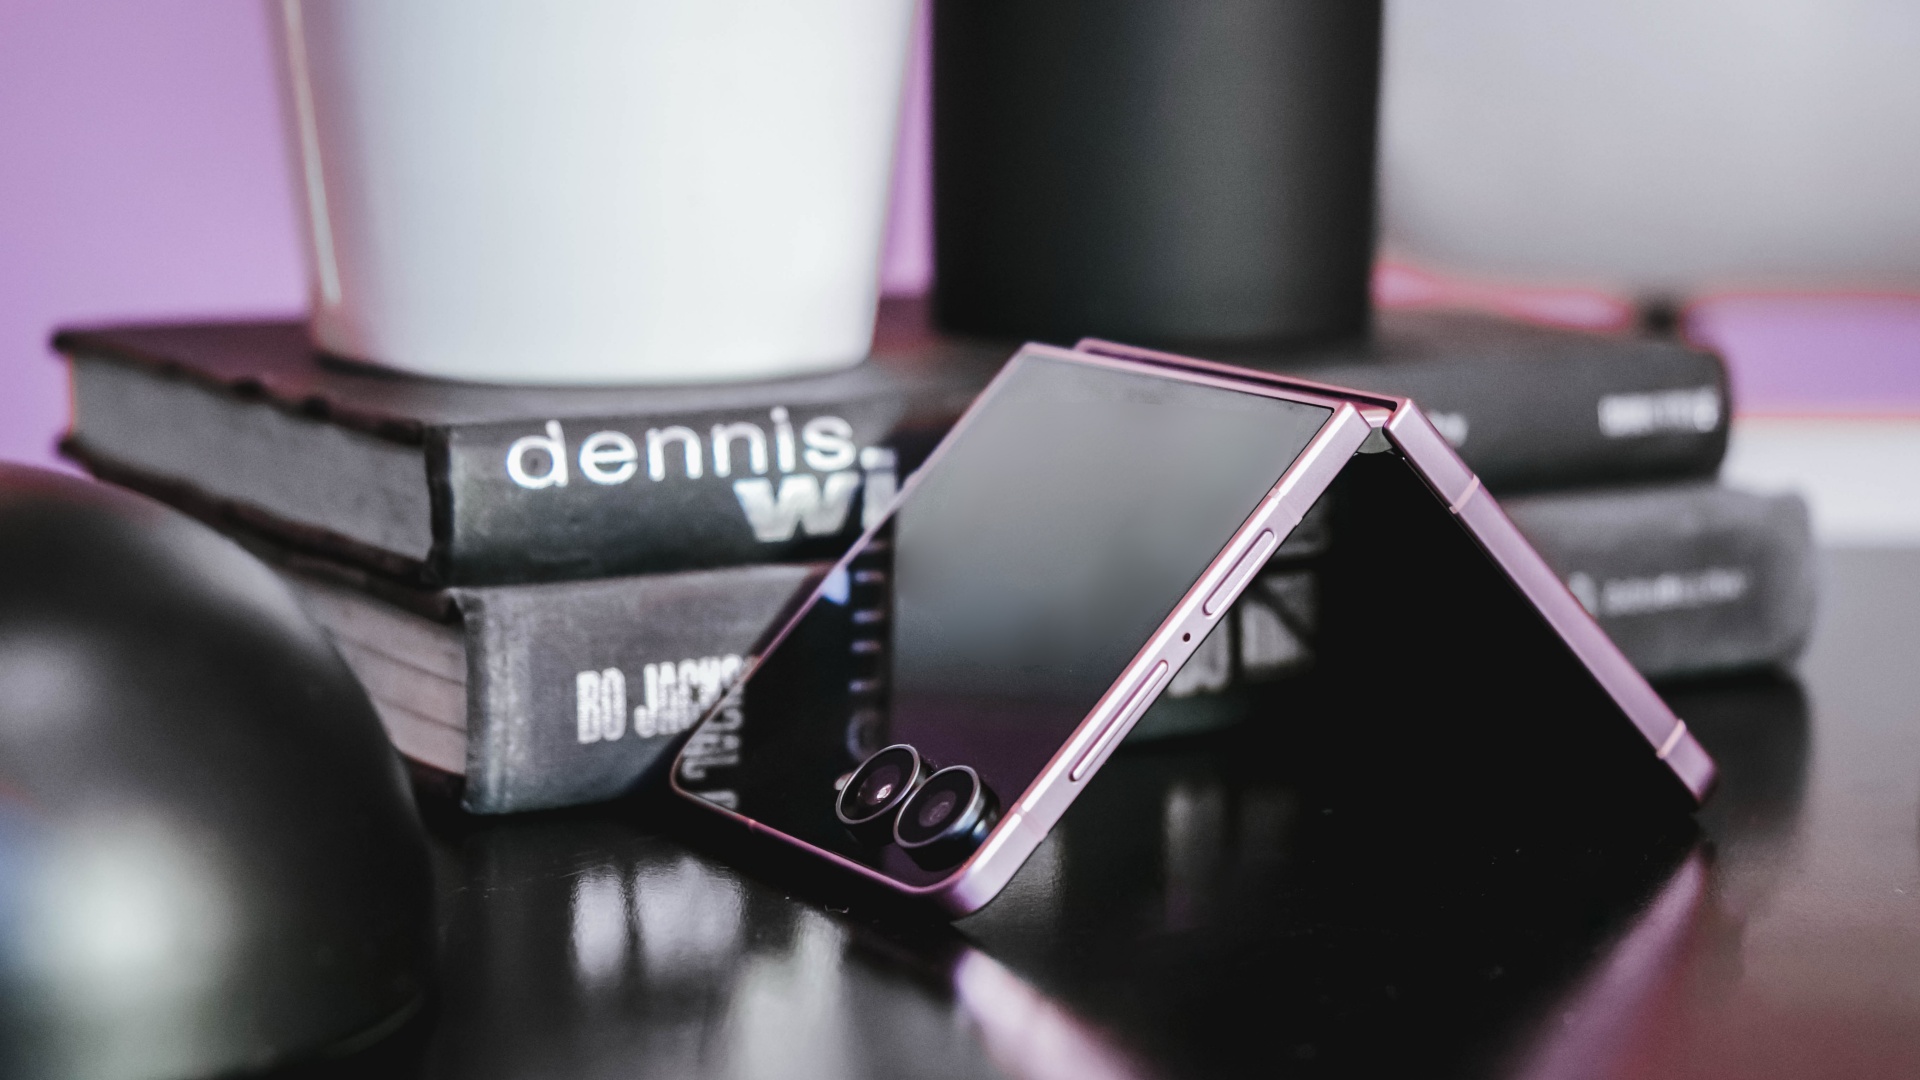
I don’t upgrade simply because there’s a newer model on the shelf.
Last year, I upgraded to the Samsung Galaxy Z Flip7 after spending three years with the iPhone 13 as my daily driver.
Even then, the decision wasn’t about chasing the latest release. It was about finding a device that better matched how I work.
I’m a firm believer that every upgrade has to earn its place in my pocket, especially when there are already perfectly capable phones sitting on my desk.
So when I decided to pre-order the Samsung Galaxy Z Flip8, the decision wasn’t simply about getting the newest device.
It came down to two questions: Is this a smart upgrade? And if it is, what’s the smartest way to own it?
The first question was answered by the device itself. The second is where Maya Mini Payments entered the conversation.
For me, the Flip8 addresses the reasons to upgrade. Maya Mini Payments addresses one of the biggest reasons people hesitate: big purchases that could be paid in 3, 6, 9 or 12 monthly payments.
Changing how I shoot and use my phone
I spend most of my day switching between shooting, editing, and posting, sometimes all within the same hour.
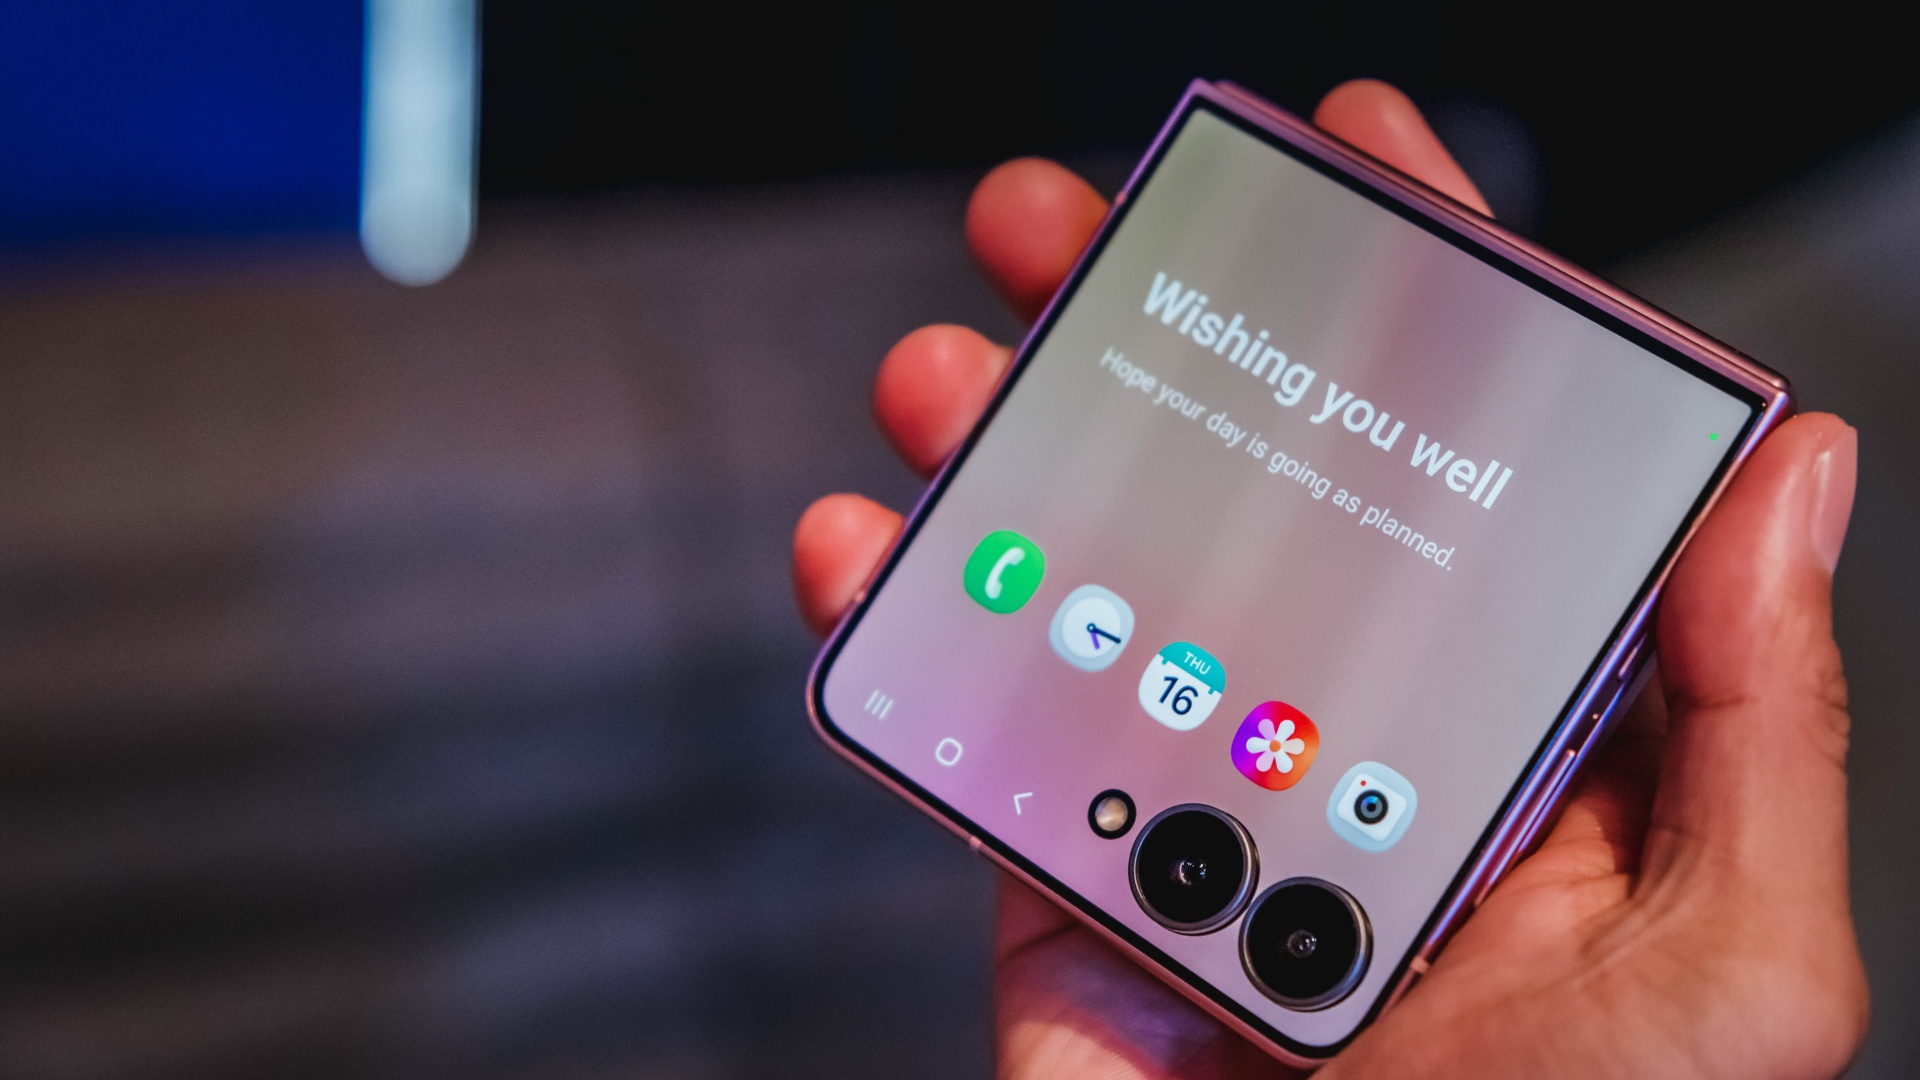
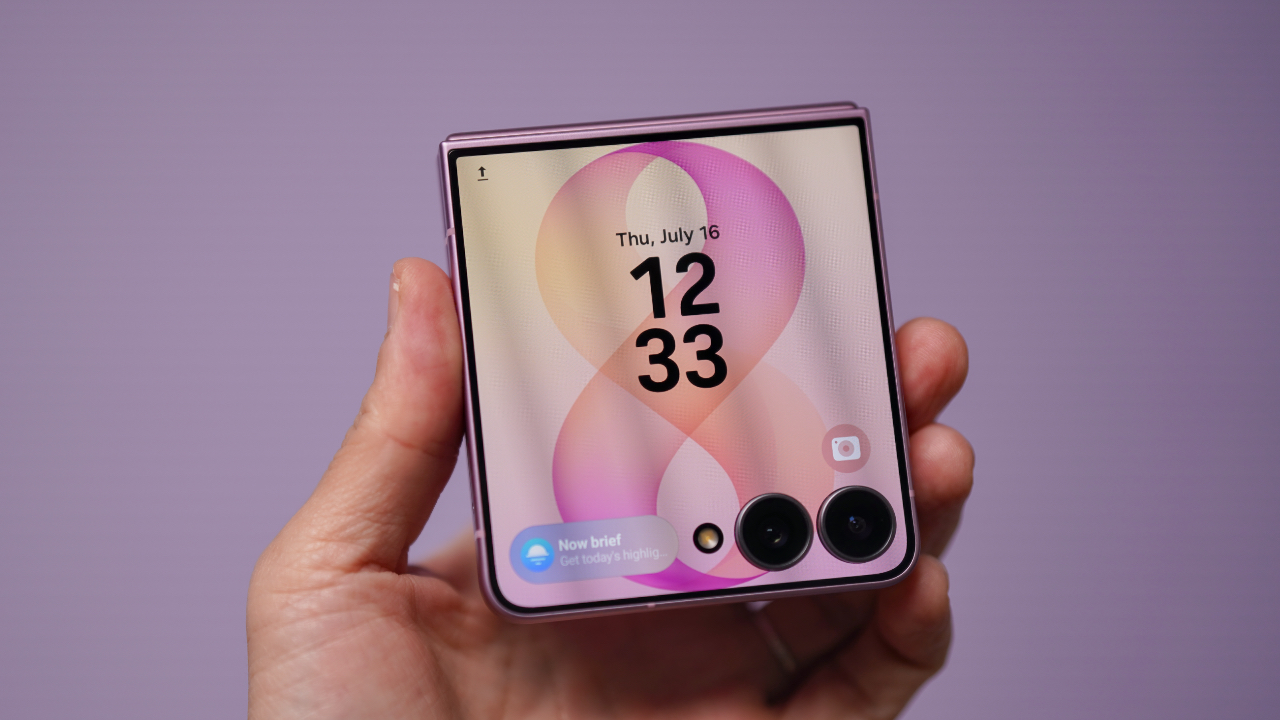
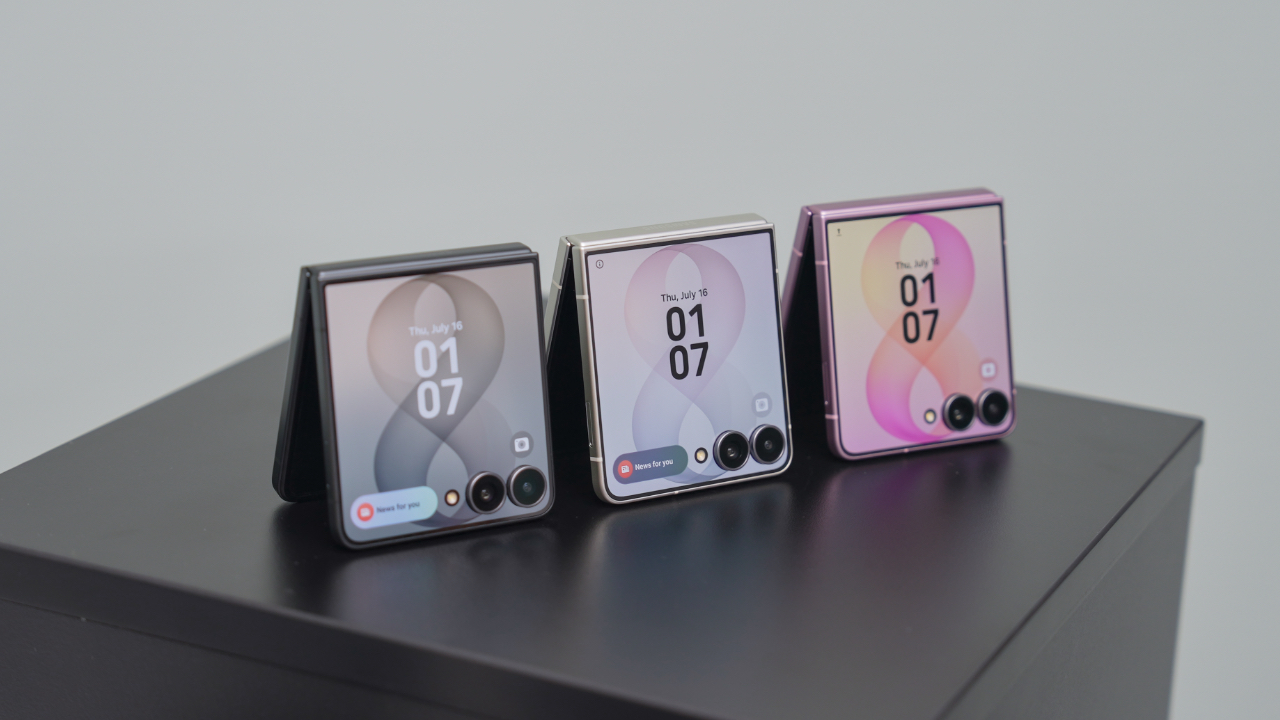
One of the biggest reasons the Galaxy Z Flip8 caught my attention is the cover screen. It’s finally useful enough that I can shoot, preview, and interact with content without constantly opening the device.
That may sound like a small change, but it makes a difference when you’re trying to capture candid moments before people notice a camera pointed at them.
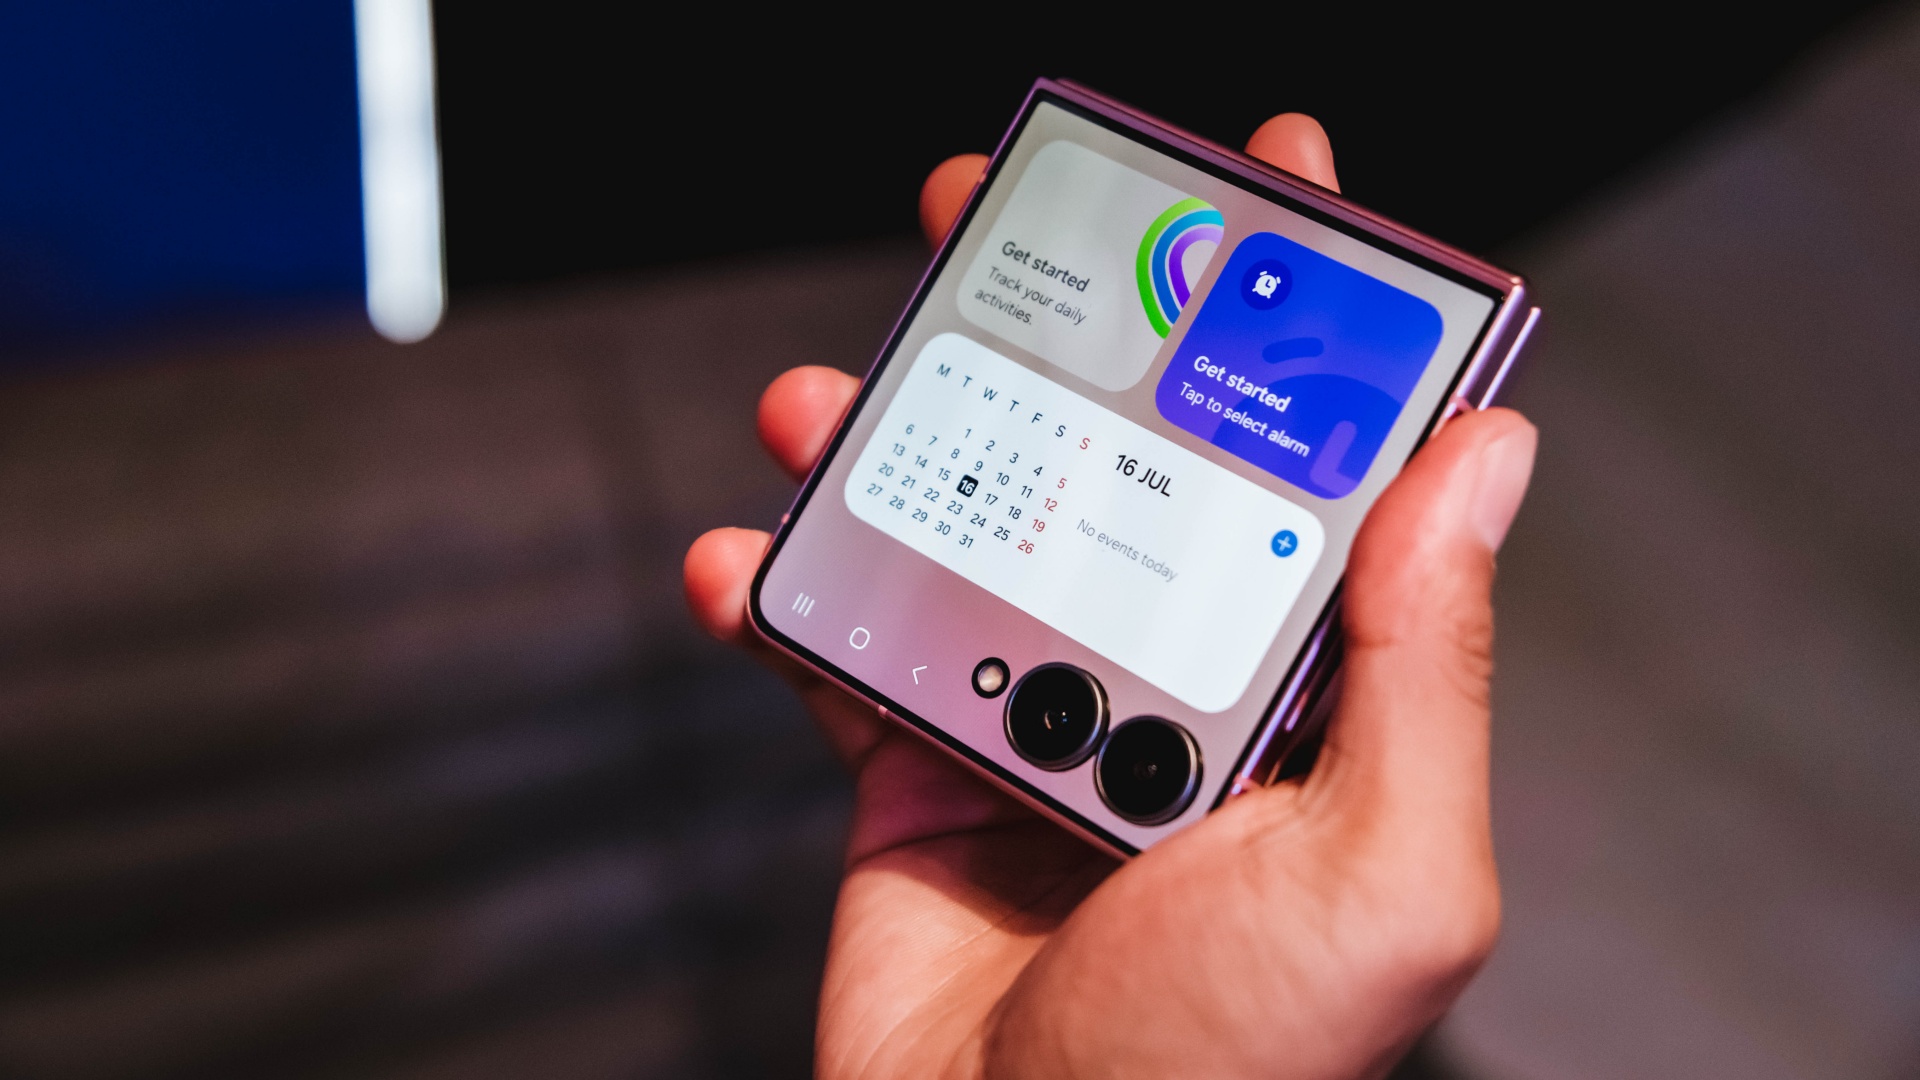
It also makes everyday tasks easier. I can check a script, review a shotlist, reply to messages, or glance at notifications without unfolding the phone every few minutes.
For years, foldables often felt like they required some compromise. You gained a unique form factor and flexibility, but sometimes gave up a little on the camera experience. The Flip8 feels like it’s closing that gap.
Samsung’s improvements in low-light performance and stabilization are especially noticeable for the kind of run-and-gun content I create.
I haven’t spent enough time with it to call this a full review yet, but my first impressions have been positive. The experience feels more refined and more dependable than previous generations.
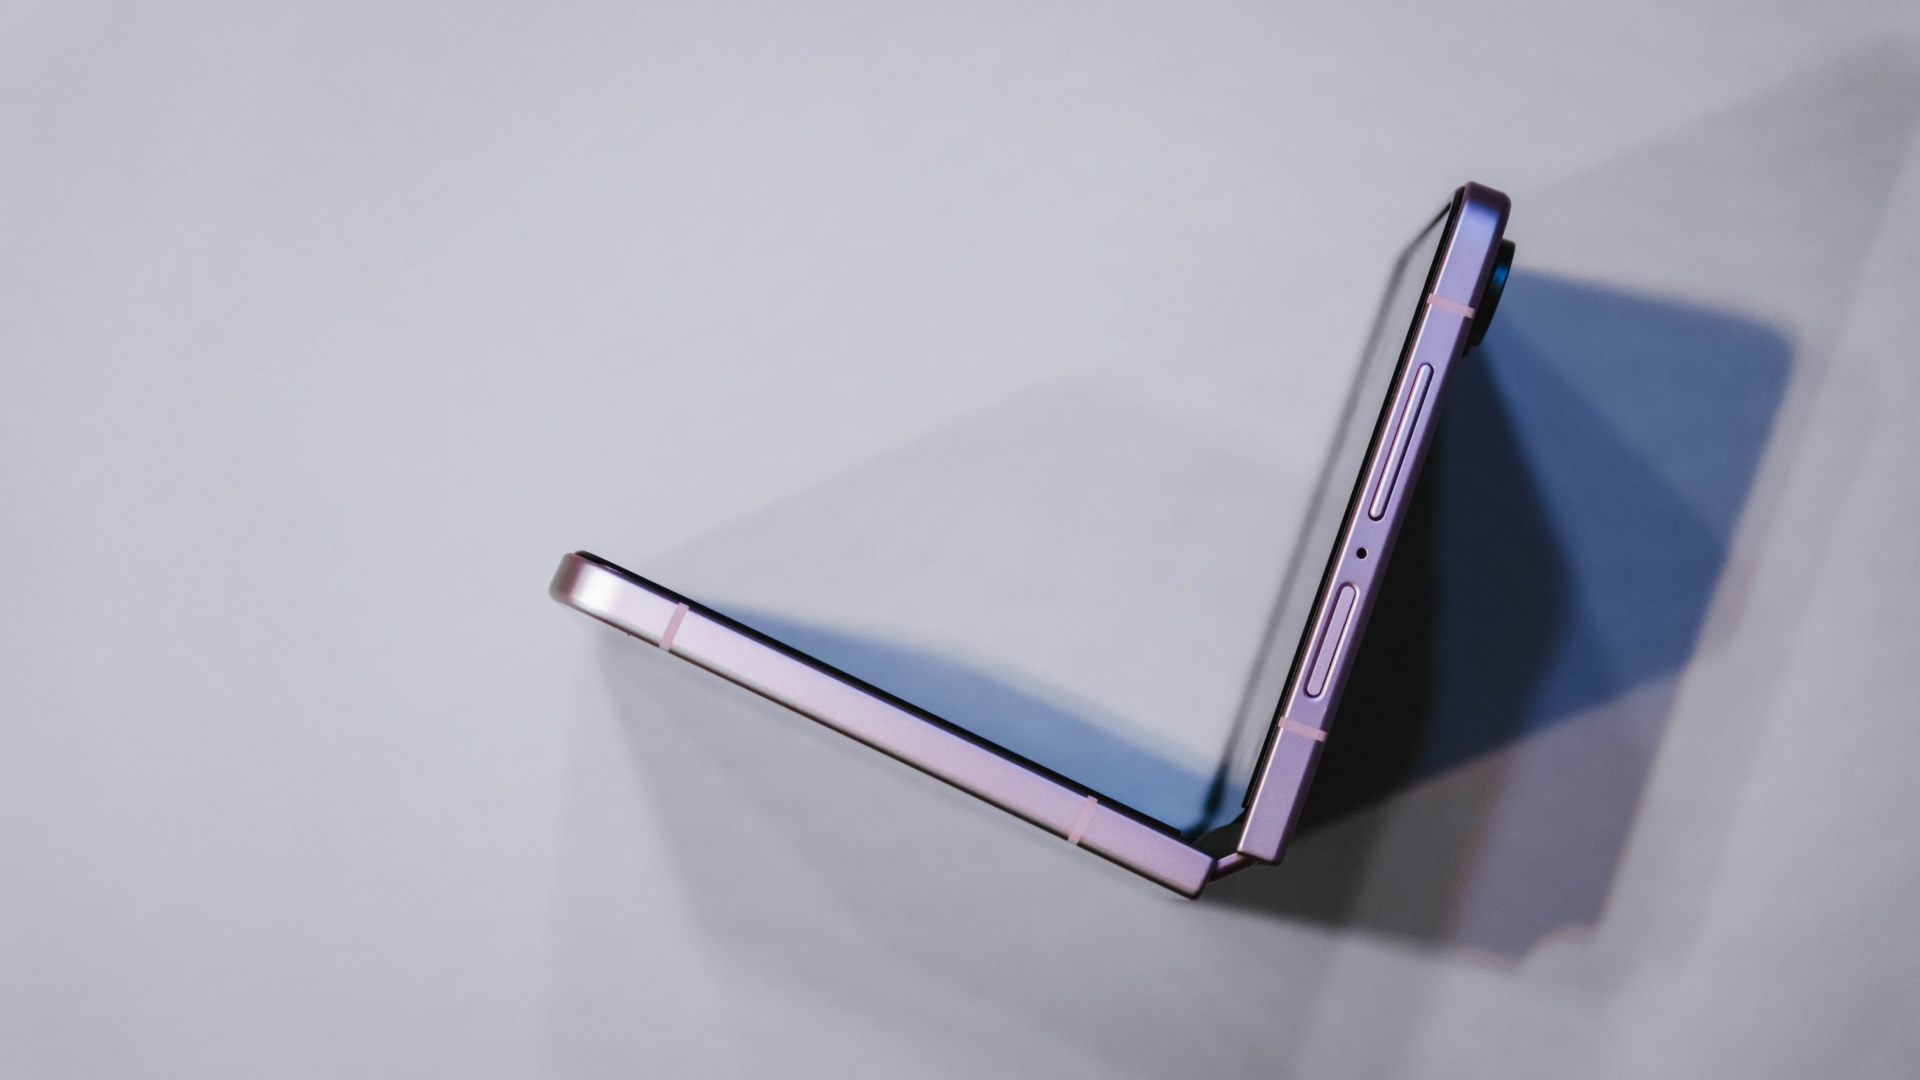
Features alone don’t convince me to upgrade. They have to solve a real problem. The more useful cover screen, the improved camera experience, and the overall refinement were the first signs that the Flip8 was offering something I’d actually use every day rather than another feature to add to a spec sheet.
The battery and multitasking finally match my day
The less exciting reason I’m upgrading is also the one that affects me the most.
Between filming, reviewing footage, answering emails, coordinating campaigns, and managing social media, my phone is constantly working.
My old device usually drops into battery-saving territory before dinner. It gets the job done, but I spend too much time thinking about charging instead of working.
The Galaxy Z Flip8 feels better equipped for that reality. The battery efficiency is improved, and multitasking feels more natural when juggling multiple apps throughout the day.
Those aren’t flashy features, but they’re the kinds of upgrades that quietly improve everyday productivity. They’re also the features that convinced me this wasn’t simply a want. It was an upgrade I could actually justify.
Once I was convinced the Flip8 was worth upgrading to, I realized the decision wasn’t really over. A smart upgrade also deserves a smart way to pay for it.
Making a big upgrade more manageable
Of course, deciding a device is worth upgrading to is only half the equation. The other half is figuring out how to pay for it.
The Galaxy Z Flip8 is a premium device, and for most people, the upfront cost is what gives them pause. That’s often where upgrade decisions get delayed, even when the device itself makes sense.
That’s why Maya Mini Payments stood out to me. Any Samsung purchase paid with a Maya Credit Card can be converted into Mini Payments directly through the Maya app, making it easier to spread the cost into monthly installments instead of paying for everything upfront in one go.
You can choose installment plans of up to 12 months at a fixed monthly add-on interest rate of 1%.
For Samsung Galaxy Z Fold8 and Galaxy Z Flip8 purchases, cardholders can enjoy a 3-month Mini Payment plan at 0% interest, making the upgrade more manageable without additional interest costs on the installment plan.
What I like about the concept is that it mirrors the reason I like the Flip8 itself.
The Flip8 makes it easy for me to shoot, edit, communicate, and multitask throughout the day. Maya Mini Payments makes it easy to purchase by turning one large expense into a payment plan that fits more naturally into a monthly budget.
Both are practical solutions to real-world problems. Also, the entire process can be managed directly within the Maya app, making it easy to track and manage installment conversions without additional paperwork.
View this post on Instagram
Still on the fence?
The Samsung Galaxy Z Flip8 feels like one of the strongest cases yet for upgrading to a foldable.
For me, the cover screen is more useful, the camera experience feels more capable, and the battery and multitasking improvements better match how I actually work every day.
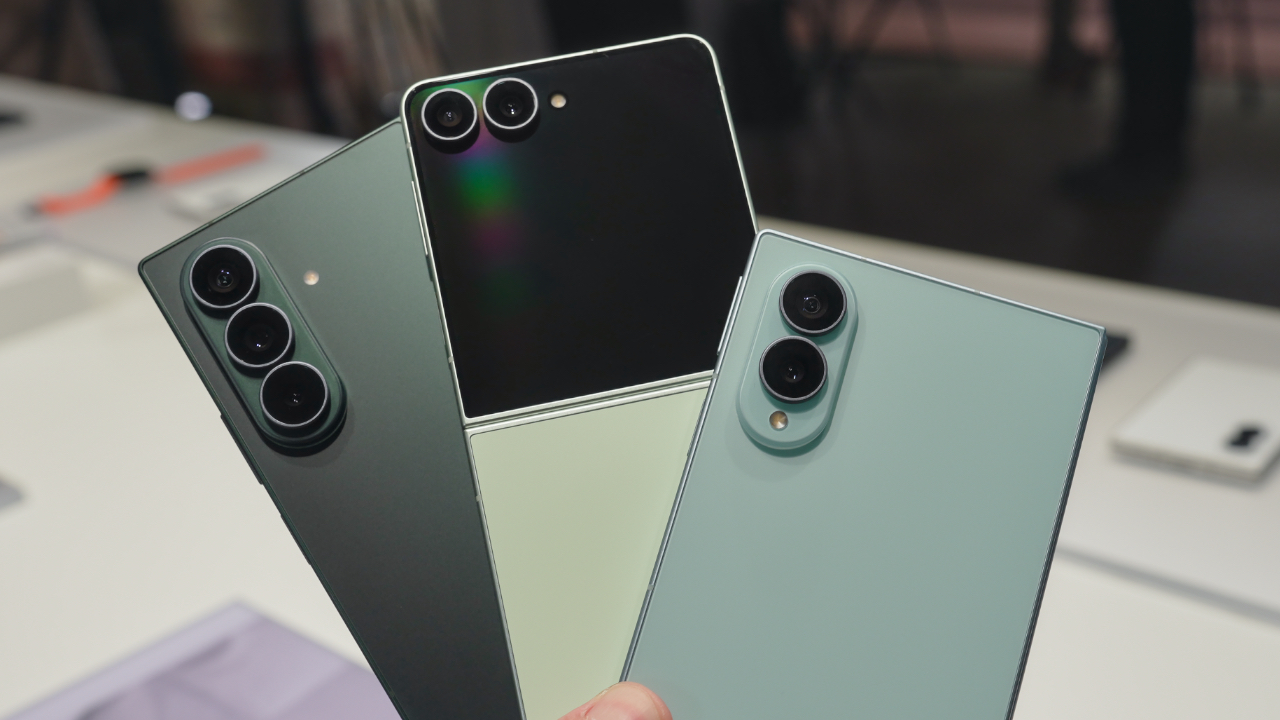
If you prefer a larger screen for productivity, the Samsung Galaxy Z Fold8 follows the same philosophy while giving users even more room to multitask and create.
If you’ve already decided Samsung’s latest foldables are your next devices, there’s also a smarter way to make that upgrade happen.
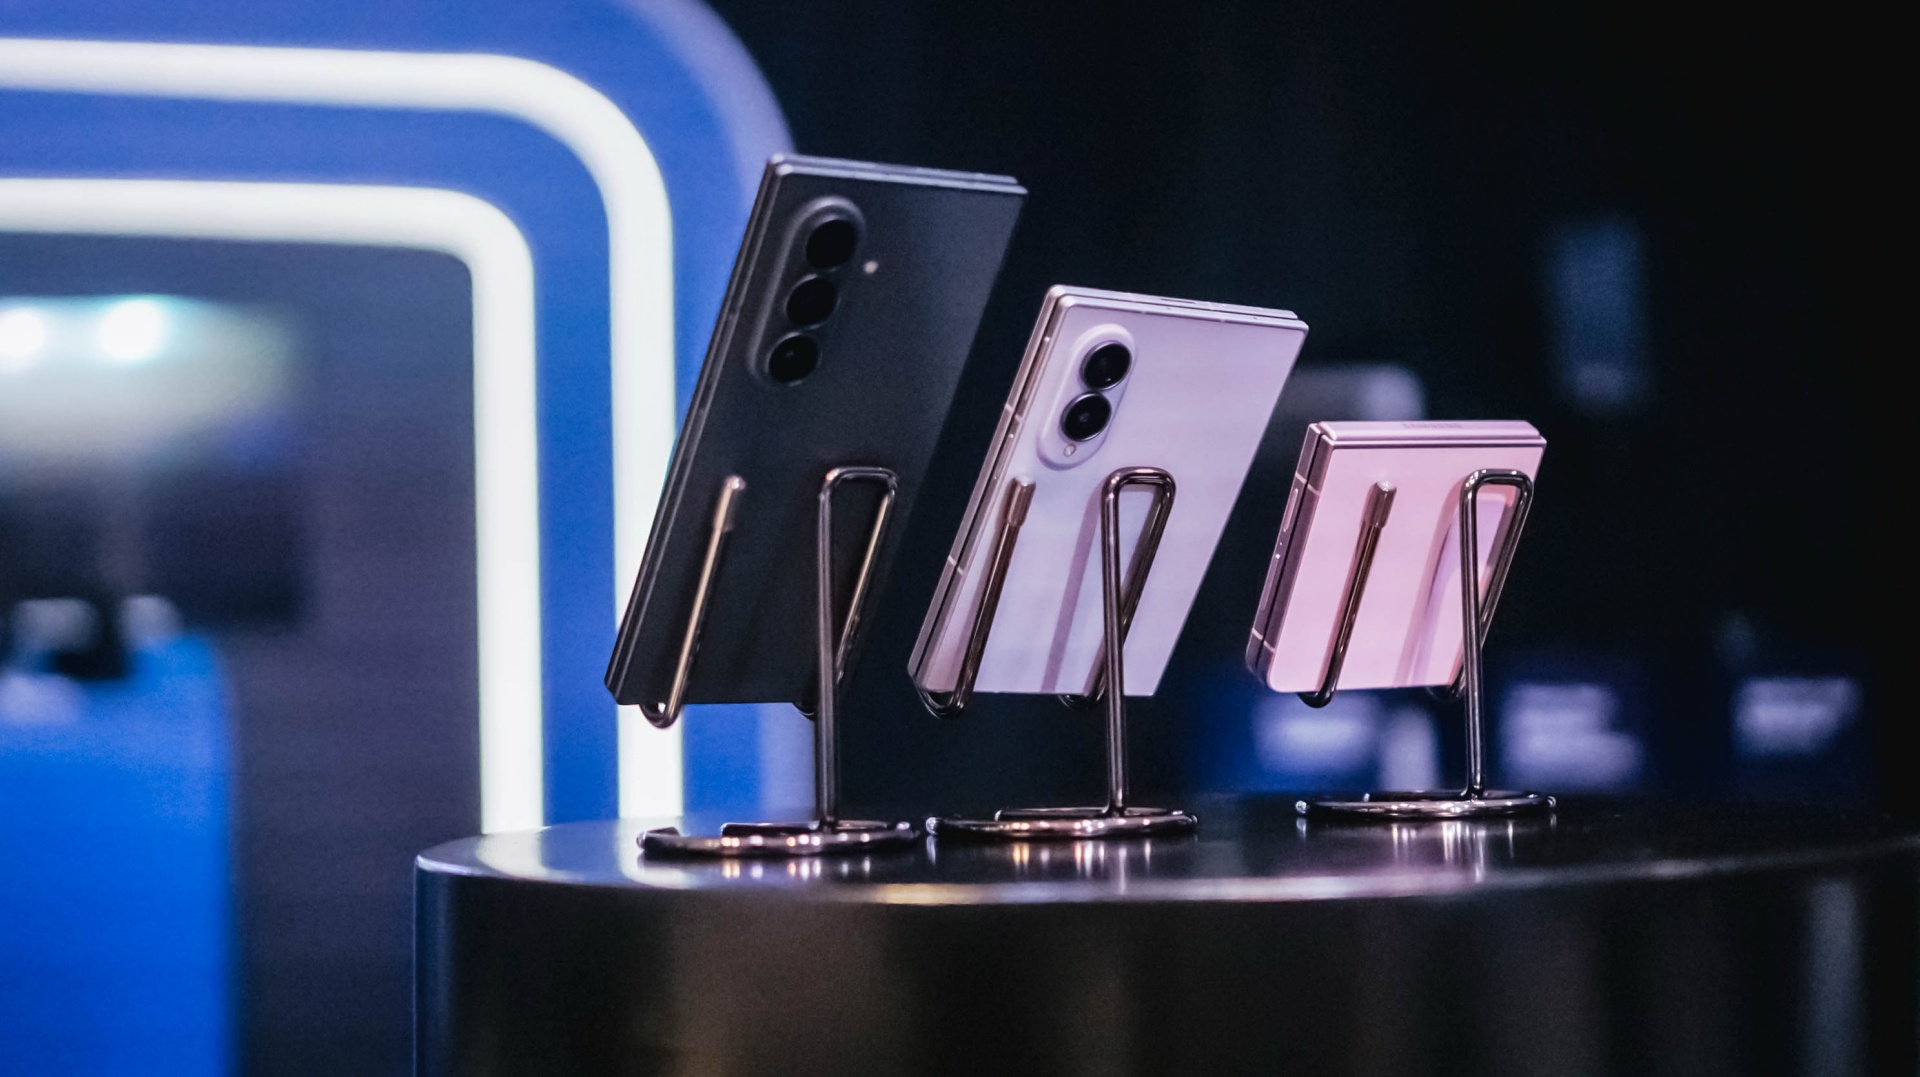
All your Samsung purchases made using a Maya Credit Card can be converted into a 3-month Mini Payment plan at 0% interest, with zero processing fees until September 30, making it easier to enjoy Samsung’s latest innovations without one big upfront payment.
Pre-orders run until August 13, with devices available in-store beginning August 14.

HP OMEN Max 16 review: Gamer-maxxing in deep black
Peripherals deemed necessary to max this out

vivo V80 review: Good phone, tough sell
A capable travel companion

Ghost of Yōtei Complete Edition review: More of a great thing
Picking up where Atsu left off

Anker soundcore AeroClip 2 brings open-ear audio to everyday life

adidas debuts ENERGYRIM carbon tech in the Adizero Adios Pro 5

Firefox ad reunites all your favorite memes from decades ago

Porsche Cayenne Electric launches in the Philippines

Nintendo eShop will finally launch in the Philippines

TECNO CAMON Slim 5G review: Slim on size, big on surprise

TECNO CAMON Slim 5G: Price, availability in the Philippines

HONOR Magic9 Pro Max launches in China with ARRI-powered imaging

BYD says that way better EV batteries are coming next year

HONOR 600S review


-
 News2 weeks ago
vivo V80 debuts with ZEISS cameras
-
 Philippines2 weeks ago
TECNO CAMON Slim 5G gets launch discounts, free MagBadge
-
 News2 weeks ago
Samsung: Galaxy Z Fold8 demand rose because of iPhone Duo
-
Reviews1 week ago
vivo V80 review: Good phone, tough sell
-
 Features2 weeks ago
I don’t want a phone that unfolds — the Galaxy Z Fold8 gets why
-
 News6 days ago
OPPO Find X10 Series: Price, availability in the Philippines
-
 Gaming1 week ago
KINGDOM HEARTS Collection [I–III] now available on PS5, Switch 2
-
 Buyer's Guide1 week ago
iPhone Duo Philippines: Prices, installments, and where to buy